Turning 65 or Over 65?
2027 Medicare Trends and Updates
Major Medicare Updates in 2027! 4 Critical Trends Every Senior Must Know: Health Plan Adjustments, Network Changes, Prescription Drug Benefit Updates, and New Medi-Cal Asset Limits.
- Medicare Market Shifts:Plan options in some areas may change or exit the market. Members should review their 2027 Annual Notice of Change (ANOC).
- Doctor Network Updates:Provider networks are changing. Re-confirm if your primary doctors, specialists, and hospitals remain in-network for 2027.
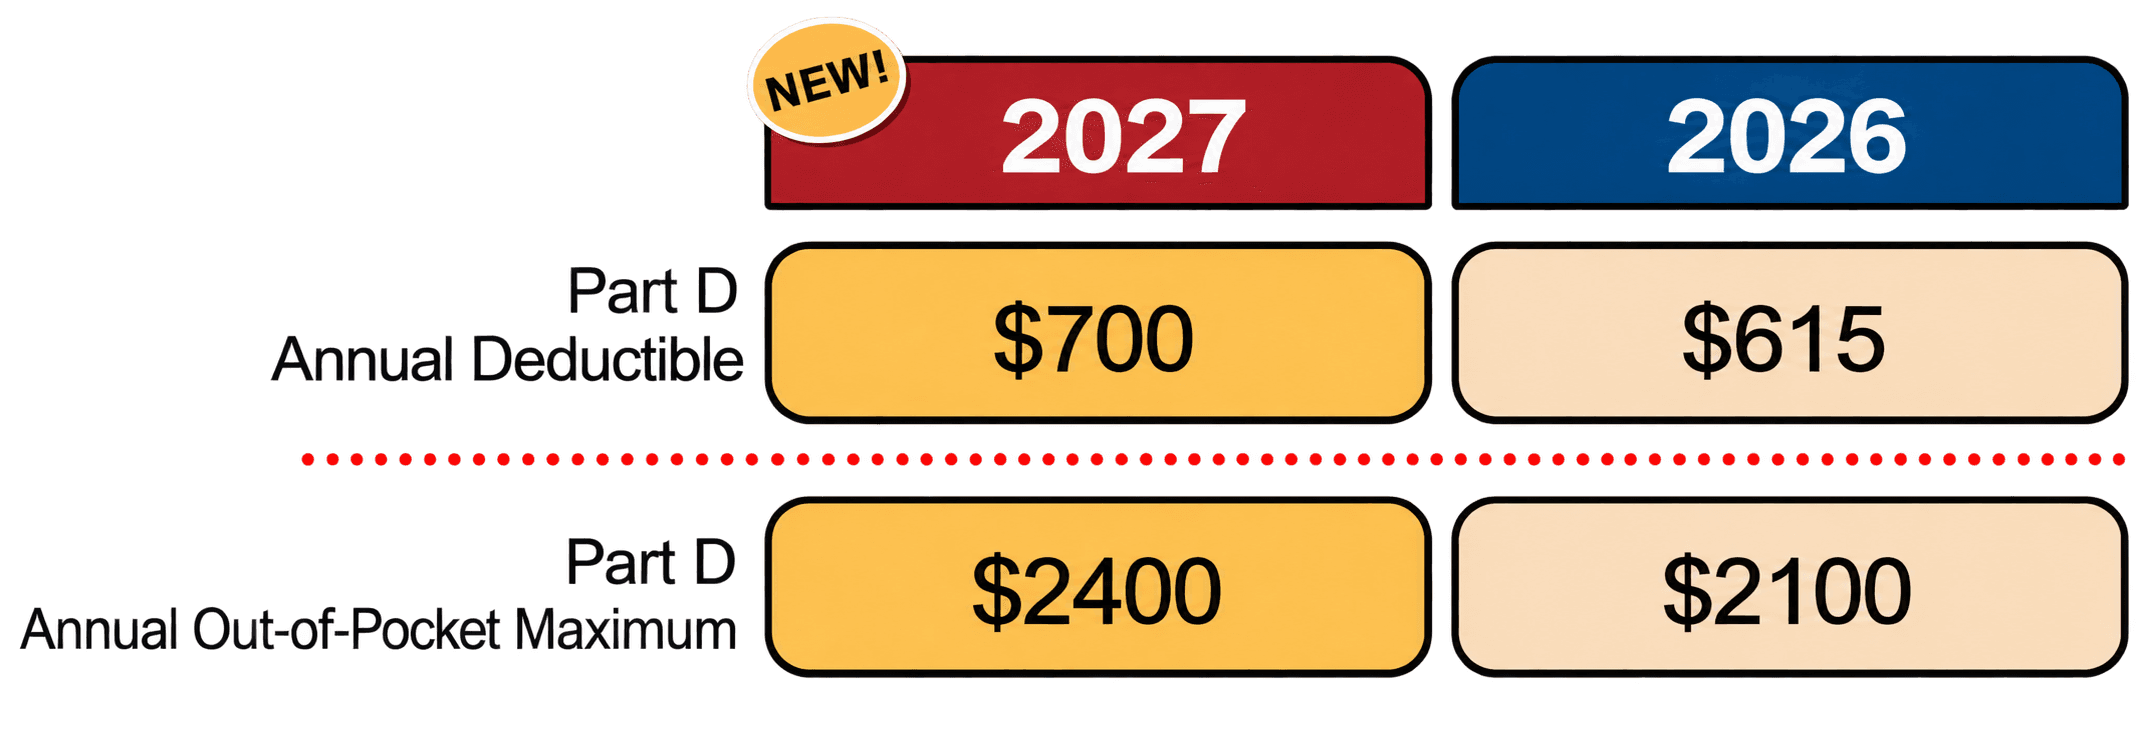
- Prescription Drug Coverage Changes:Part D annual deductibles rise to $700, with out-of-pocket maximums at $2,400. Formularies and copays are also shifting.
- California Medi-Cal Asset Limit Changes (opens in new tab):Effective July 1, 2027, asset limits drop from $130,000 to $21,000 for individuals, and $195,000 to $31,000 for couples.
2027 Medicare Big Changes: Is Your Current Plan Still the Best Fit?
2027 Medicare Trends and Key Changes
Major Medicare changes are coming in 2027. Is your current plan still the best fit?
Take advantage of the Medicare Annual Enrollment Period (Oct 15 to Dec 7) to review and adjust your coverage for next year. Stay informed and compare your options early to secure the best healthcare protection for your needs!
Major Medicare Updates in 2027! 4 Critical Trends Every Senior Must Know: Health Plan Adjustments, Network Changes, Prescription Drug Benefit Updates, and New Medi-Cal Asset Limits.
- Medicare Market Shifts:Plan options in some areas may change or exit the market. Members should review their 2027 Annual Notice of Change (ANOC).
- Doctor Network Updates:Provider networks are changing. Re-confirm if your primary doctors, specialists, and hospitals remain in-network for 2027.
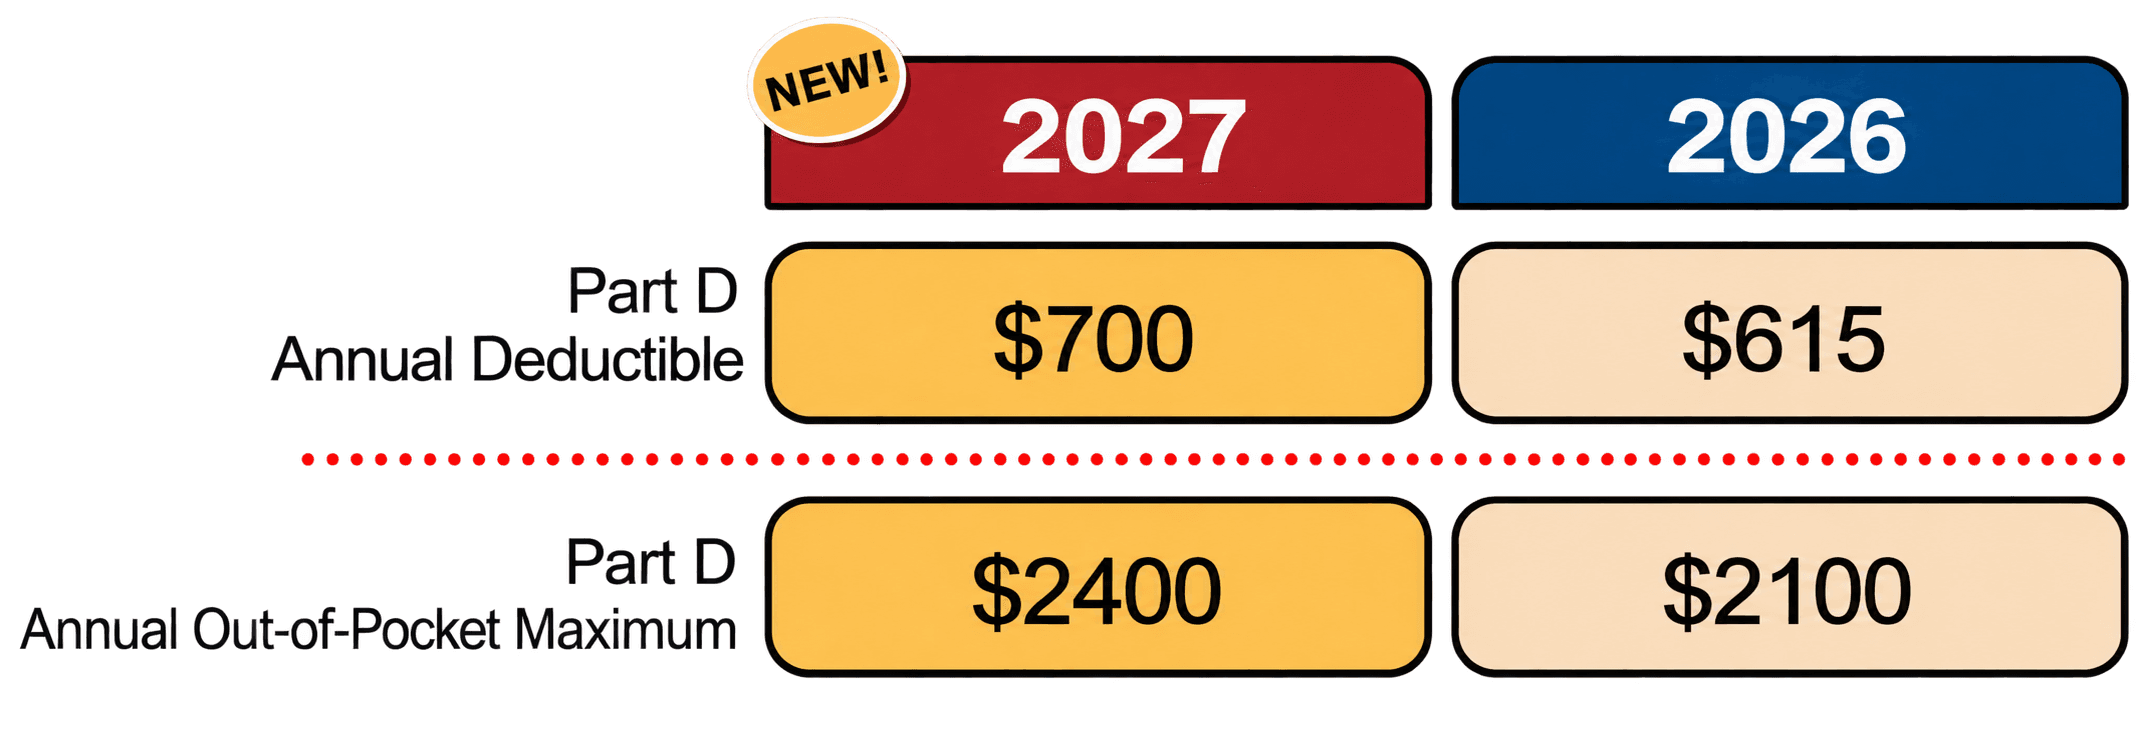
- Prescription Drug Coverage Changes:Part D annual deductibles rise to $700, with out-of-pocket maximums at $2,400. Formularies and copays are also shifting.
- California Medi-Cal Asset Limit Changes (opens in new tab):Effective July 1, 2027, asset limits drop from $130,000 to $21,000 for individuals, and $195,000 to $31,000 for couples.
What is Medicare?
As you approach retirement, have you made plans to protect your health in this new chapter of life? The U.S. government provides a dedicated health insurance program — Medicare for people aged 65 and over, as well as for certain individuals with disabilities or serious illnesses. KCAL Insurance would like to remind you that each year, from October 15 to December 7, is the brief Medicare Annual Enrollment Period. During this time, seniors can add, cancel, or switch their current health insurance plans. Our experienced Medicare consultants at KCAL Insurance are here to provide you with the most professional advice, the best prices, and the most comprehensive coverage.
You may be eligible to apply for Medicare if you meet the following conditions:
- You are a U.S. citizen or a green card holder who has lived in the U.S. for at least five years.
- You are 65 years of age or older, or meet eligibility due to disability or certain serious illnesses.
You must apply for Medicare at your local Social Security office or online (online application portal (opens in new tab)) during the three months leading up to your 65th birthday.
Our Products
When you become eligible for Medicare, you are automatically entitled to Part A (hospitalization) and Part B (outpatient services) benefits upon enrollment. However, Medicare only covers 80% of medical expenses. The remaining 20% requires the help of a professional health insurance consultant, who can recommend additional benefit packages tailored to your financial situation and health needs — ensuring that high medical costs won’t become a burden in your retirement years.
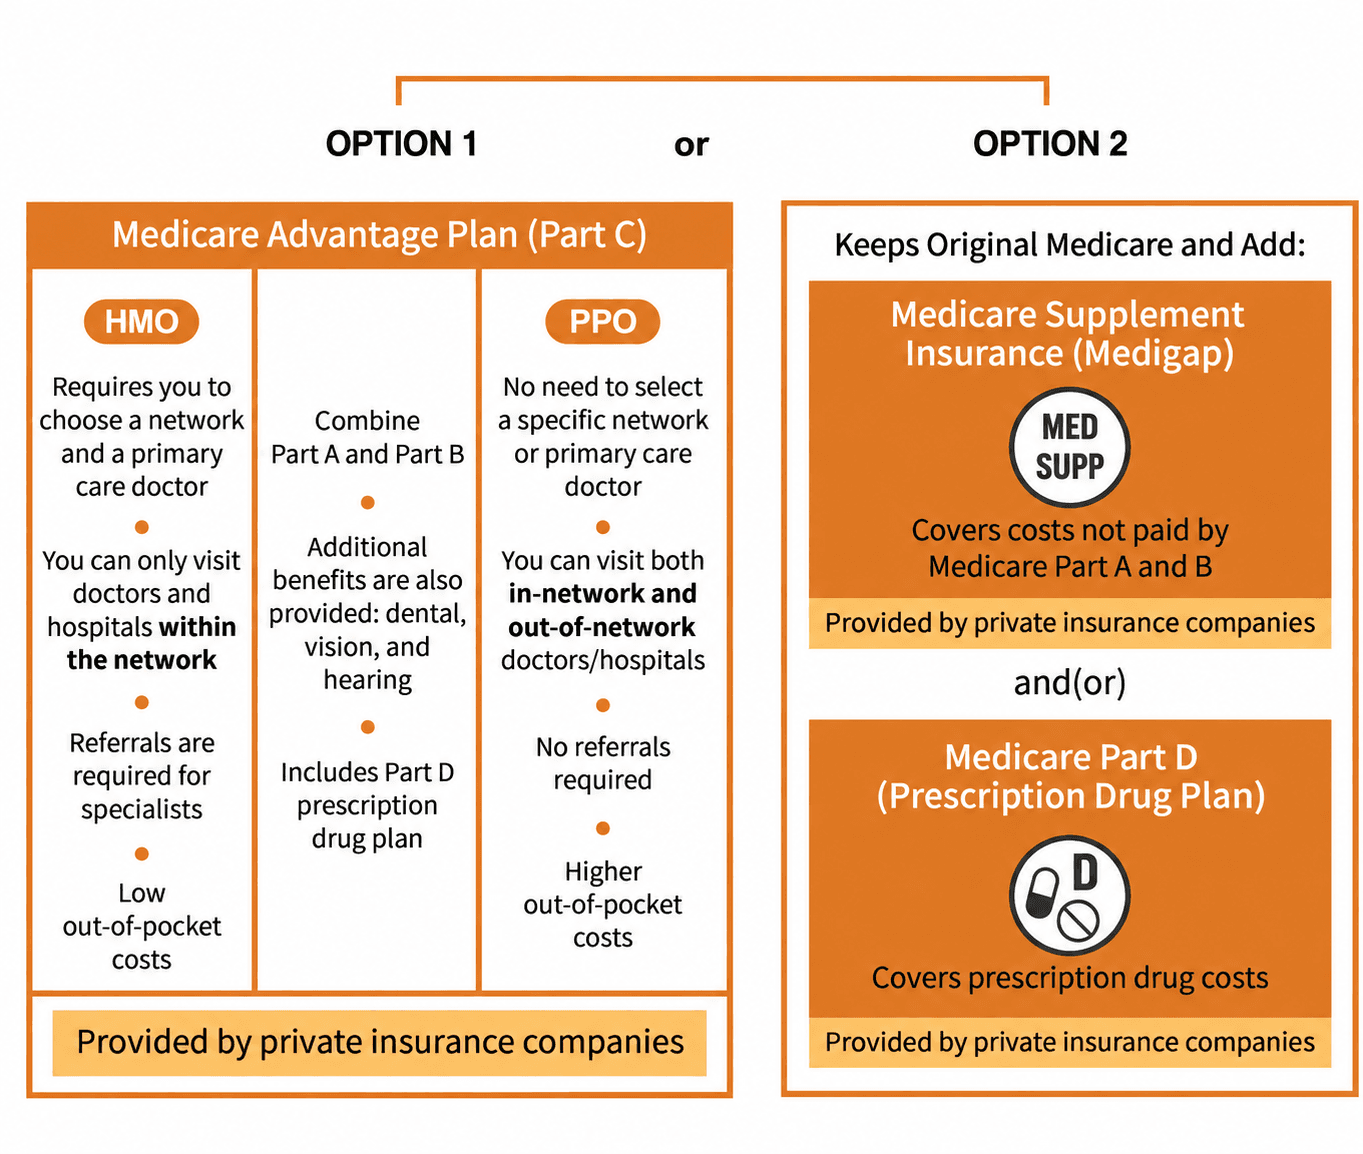
Offered by private health insurance companies, this plan supplements the coverage not provided by original Medicare. It combines Part A hospital and Part B outpatient benefits, and offers extra benefits such as dental, vision, and hearing coverage, as well as prescription drug coverage. For HMO plans, members must choose a primary care physician and receive medical services within a designated provider network. The plan also includes prescription drug benefits. A referral from a primary care physician is required to see specialists.
Also offered by private health insurance companies, this plan supplements original Medicare coverage. It combines Part A hospital and Part B outpatient benefits, with additional benefits like dental, vision, hearing, and prescription drug coverage. PPO plan members are not required to choose a primary care physician or stay within a provider network. They can visit both in-network and out-of-network doctors and hospitals without a referral.
Private health insurance companies offer these plans to fill in the gaps left by original Medicare coverage. There are no network restrictions, and usage is not limited by county or state.
Private health insurance companies offer plans that help cover the cost of prescription drugs. Different plans provide various levels of drug coverage and co-payment rules, depending on the drug tier and plan design.
Compare Your Medicare Options
Option 1: Medicare Advantage Plan (Part C)
Medicare Advantage plans are offered by private insurance companies and combine your Medicare Part A and Part B coverage. Many plans may also include extra benefits such as dental, vision, hearing, and prescription drug coverage.
- Requires you to choose a primary care doctor and use a specific provider network.
- Generally only covers care from in-network doctors and hospitals, except in emergencies.
- Referrals are usually required to see specialists.
- Often has lower out-of-pocket costs compared to other plan types.
- May combine HMO-style coordinated care with some out-of-network flexibility.
- Allows you to see certain providers outside the network, usually at a higher cost.
- Can offer a balance between structure and flexibility.
- Still managed by a private insurance company under Medicare rules.
- Does not require you to choose a primary care doctor.
- Lets you see both in-network and out-of-network providers.
- Referrals are generally not required for specialists.
- Typically higher premiums or out-of-pocket costs than HMO plans.
Option 2: Keep Original Medicare and Add Coverage
With this option, you keep Original Medicare (Part A and Part B) and add private coverage to help with out-of-pocket costs and prescription drugs.
- Helps pay some costs not covered by Medicare Part A and Part B, such as deductibles, copays, and coinsurance.
- Can reduce your out-of-pocket expenses when you use Medicare-covered services.
- Policies are standardized by plan letter, but premiums vary by insurer.
- Offered by private insurance companies.
- Helps cover the cost of prescription drugs.
- Each plan has its own formulary (list of covered drugs) and pharmacy network.
- Premiums, copays, and coinsurance vary by plan and medication tier.
- Offered by private insurance companies approved by Medicare.
When can I apply for Medicare?
Initial Enrollment Period:When you turn 65 or become eligible for Medicare due to other reasons, you can use your initial enrollment period. Your initial enrollment period starts three months before your 65th birthday month, includes your birthday month, and ends three months after your birthday month (a total of seven months).
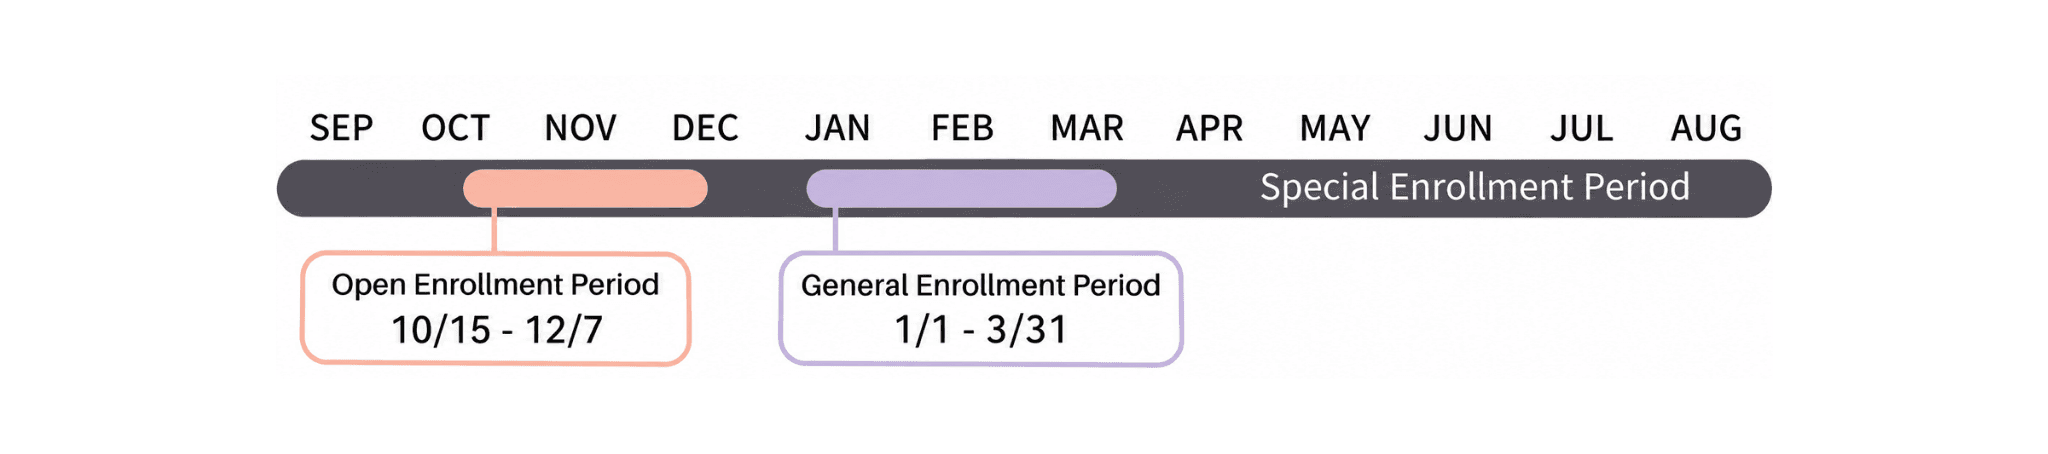
Annual Enrollment Period:From October 15 to December 7 each year, you can add, cancel, or switch Medicare plans.
Special Enrollment Period:In certain special situations, you may qualify for a special enrollment period. For example, if you retire and lose employer coverage, are diagnosed with certain qualifying disabilities or chronic illnesses, receive assistance from the state government, or move out of your plan’s service area.
We’ve Selected the Top Insurance Carriers for You
More Exciting Videos for Seniors
Disclaimer: KCAL Insurance Agency (CA License #0B07015) and Bao Insurance Services (CA License #6004170) provide information and services related to Medicare Advantage, Medicare Supplement, and Medicare Part D Prescription Drug Plans.
We do not offer every plan available in your area. Currently, we represent 16 organizations that offer more than 100 products in your area. Please visit www.medicare.gov (opens in new tab), call 1-800-MEDICARE (TTY users should call 1-877-486-2048, 24 hours a day/7 days a week).